Commodity Explorer, Wednesday, October 7, 2026
Published Oct 14, 2026, 9:15 AM ET
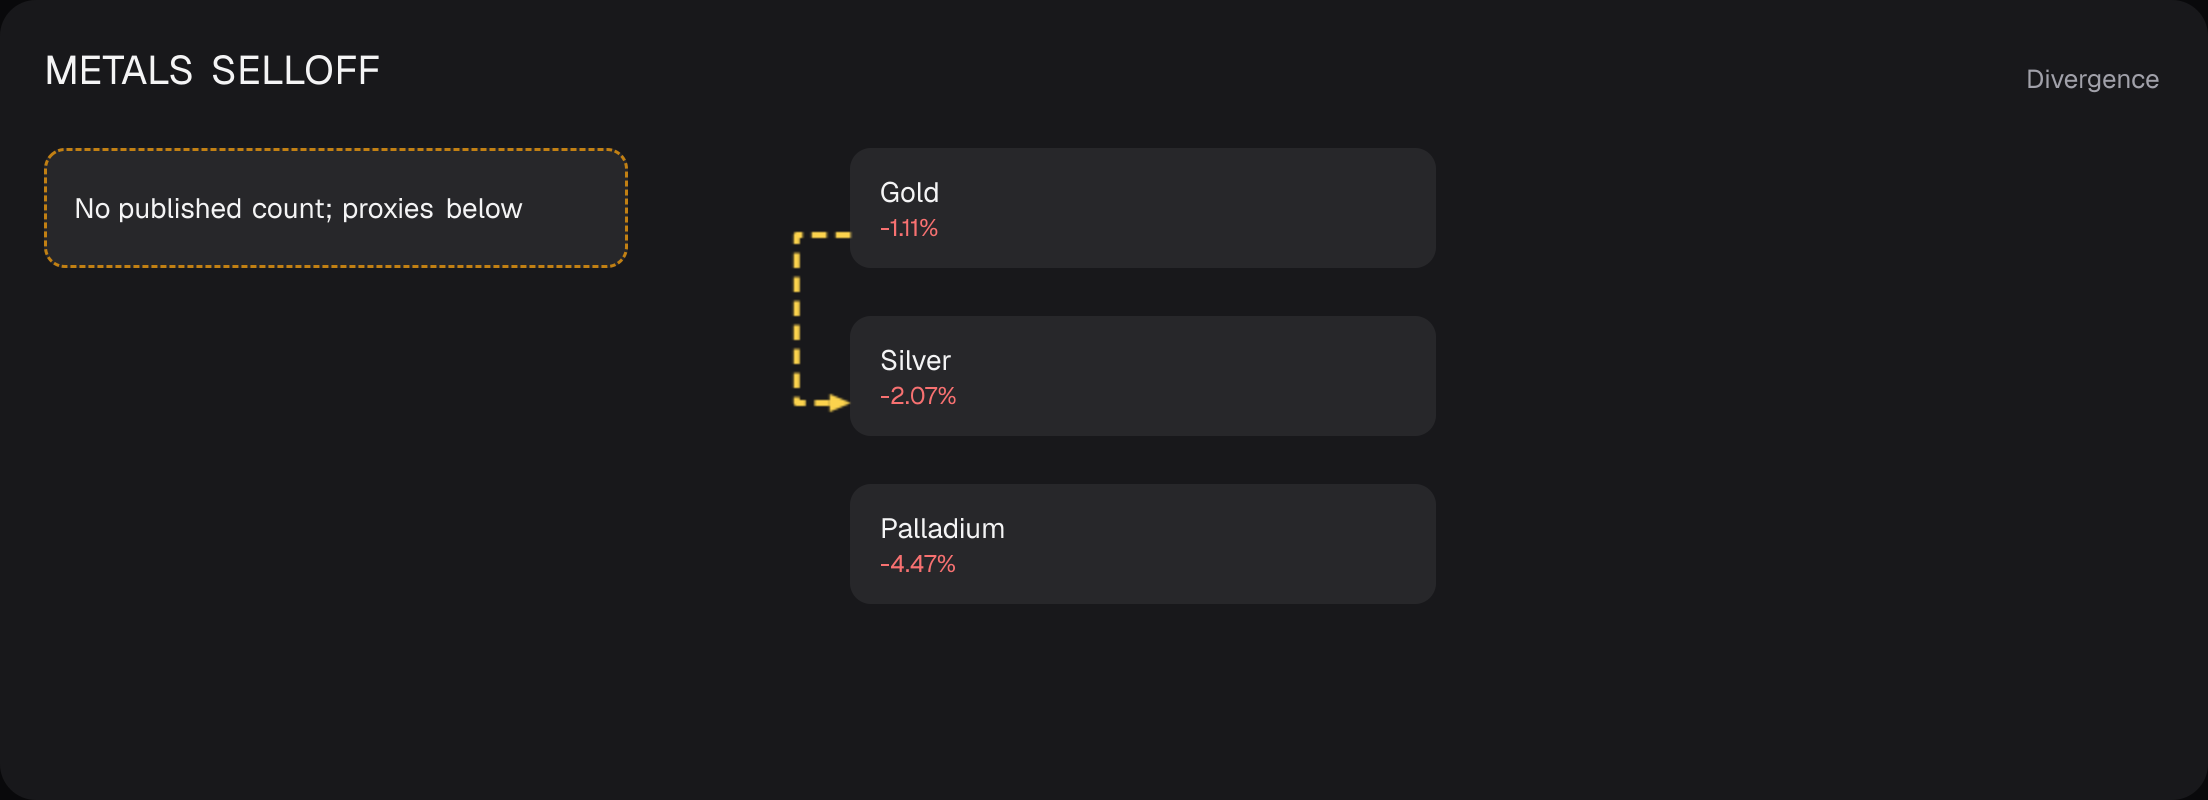
On October 7 Broad Commodities (DBC) fell 0.6%. The lead story on the diagram is METALS SELLOFF, traced through 4 steps.
Commodity Explorer as drawn for the share card of Wednesday, October 7, 2026. The same picture is on its share card.
What is moving inside the physical commodity economy, why it may be moving, and where the effect goes next. Tap a commodity to move. Every move here is measured between two stored daily closes, so the reading belongs to a session rather than to a time of day.
Colour marks direction only. A commodity rising is a cost to whoever buys it and revenue to whoever sells it, so nothing here is drawn as good or bad news.
Today's relationship
Copper
Copper made the largest move on the board.
Wiring, motors and construction. An industrial-demand read, and not a perfect one.
- Copper+6.9%
Stored daily closes.
2 of 5 metals names moved today, the largest being Palladium at -4.47%. Divergence is the relationship worth reading here.
Gold and silver fell together but silver's deeper drop against gold's smaller one separates haven selling from industrial demand weakness, with no upstream reading to explain it.
Divergence. Copper against gold: +0.03% against -1.11% today, and the spread between them sits 1.5 standard deviations from its own average over the last 60 stored sessions. The classic growth against haven reading. Informative, and not a forecast of either.
Stored connections, each labelled by what it is. Only a Measured line is read as a driver.
Managed-money net is +20.1% of open interest as of Tuesday 2026-10-06, down 5.8 points on the week: a change that cleared the bar set by this contract's own stored history. Positioning, never a physical driver.
CFTC report, published weekly: context and not a same-session cause.
Copper against gold: Diverging, 1.5 standard deviations from its own average over the last 60 stored sessions. The classic growth against haven reading. Informative, and not a forecast of either. Gold -1.11% against Copper +0.03% on the session.
Industrials fund (XLI): -2.18% on 2026-10-07. Equipment and construction makers buy copper. A sector fund stands for the nearest listed buyers and is not a measured link.
Materials fund (XLB): -1.51% on 2026-10-07. Miners sell copper, so this fund holds the revenue side of the market. A sector fund stands for the nearest listed buyers and is not a measured link.
Consumer Discretionary fund (XLY): -0.32% on 2026-10-07. It is the sector end of the Sector Supply Lines path Copper to technology, autos and industrials, a stored link that is not a measured one. A sector fund stands for the nearest listed buyers and is not a measured link.
Top to bottom: Upstream connections, Commodity, Where it goes
- Physical flow
- Divergence
The dollar index moved +0.44% on the session (close of 2026-10-07). Macro context, not tested against this market.
abrdn Palladium ETF Trust shares outstanding +7.8%Proxyabrdn Palladium ETF Trust shares outstanding is 28.84 million shares in its quarterly reading dated 2026-09-30, +7.8% against 26.75 in the prior published quarter (2026-06-30). The fund's share count at each quarter end from its SEC filings. It counts shares and not ounces, and moves only when the fund creates or redeems shares. A proxy for palladium held by the fund between filings, not a count of it. Source: SEC EDGAR filings of the trust. A quarterly published figure, so not a measure of the latest close.
Gold in London vaults +2.0%Gold in London vaults is 315.8 million troy ounces in its monthly reading dated 2026-09-30, +2.0% against 309.7 in the prior published month (2026-08-31). The month-end count of gold held in the vaults of London bullion banks, published about a month in arrears. Metal held in London vaults only, which is not the world's stock. Source: London Bullion Market Association. A monthly published figure, so not a measure of the latest close.
India gold imports (customs, HS 7108) -20.4%ProxyIndia gold imports (customs, HS 7108) is 36.1 tonnes in its monthly reading dated 2026-08-31, -20.4% against 45.4 in the prior published month (2026-07-31). Tonnes of unwrought and semi-manufactured gold India's customs recorded as imported, one reporter of the largest physical gold markets, published a month or two late. A proxy for physical gold demand in one large market, not a count of it. Source: UN Comtrade, as reported by India. A monthly published figure, so not a measure of the latest close.
US primary metals industrial production (monthly output index) +1.0%ProxyUS primary metals industrial production (monthly output index) is 105.1 index points (2017 = 100) in its monthly reading dated 2026-10-01, +1.0% against 104.0 in the prior published month (2026-09-01). Monthly output of US makers of iron, steel and nonferrous metals, of which copper is one part. It measures how much metal US plants produced and not how much is held in any warehouse, so it is not a stock or inventory level of copper. It is revised in later releases. A proxy for demand from US metal makers, copper among them, not a count of it. Source: Board of Governors of the Federal Reserve System, via FRED. A monthly published figure, so not a measure of the latest close.
The downstream column stops at the first physical use. Where a cost travels after that, through industries and equity sectors, is Sector Supply Lines' subject and not this page's.
Upstream
Pairs
Downstream
Trades against
Every commodity
Energy
Metals
Grains
Livestock
Softs
Broad basket
- 1
Corn Belt rainfall sits at its highest reading in fifteen years for this window yet corn condition still lags its five year average, an unusual pairing where abundant moisture has not lifted crop quality.
- 2
Gold and silver diverging alongside palladium's much larger drop together suggest the metals weakness is concentrated in industrial and growth linked demand rather than haven flows alone.
- 3
Crude and diesel are reconverging even as Brent and WTI pull further apart, suggesting the US benchmark is moving on a distinct pressure from the rest of the barrel.
What it costs to move it
- Long-distance truckload230.99+5.61%What long-haul truckload carriers actually charged. This is the rate side of the trucking path, where the diesel price is the fuel side.index, published monthly, observation of 2026-10-01, measured against 2026-09-01. US Bureau of Labor Statistics producer price indexes, retrieved from FRED.
- Truck transportation, all230.3+3.55%The broader trucking read. It and the truckload index moving apart separates the long-haul contract market from everything else on the road.index, published monthly, observation of 2026-10-01, measured against 2026-09-01. US Bureau of Labor Statistics producer price indexes, retrieved from FRED.
- Freight arrangement136.40.00%The intermediary's price. It typically moves ahead of the carrier indexes, because a broker reprices a load in a day and a contract carrier reprices at renewal.index, published monthly, observation of 2026-10-01, measured against 2026-09-01. US Bureau of Labor Statistics producer price indexes, retrieved from FRED.
- Line-haul railroads272.19+0.04%The billed-rate read on rail, which the weekly grain shuttle rate above is the grain-specific and faster-moving half of.index, published monthly, observation of 2026-10-01, measured against 2026-09-01. US Bureau of Labor Statistics producer price indexes, retrieved from FRED.
- Rail freight, commodity basis159.05+0.04%A second rail rate built a different way. Where it and the line-haul industry index agree, the rail reading is not an artefact of one construction.index, published monthly, observation of 2026-10-01, measured against 2026-09-01. US Bureau of Labor Statistics producer price indexes, retrieved from FRED.
- Shuttle rail, grain134+3.08%What a grain shipper actually pays for a shuttle railcar, indexed against the 2017 average of $4,833.14 a car.index, 2017 = 100, published weekly, observation of 2026-10-07, measured against 2026-09-30. USDA Agricultural Marketing Service, Grain Transportation Report.
- Illinois River barge, grain248.92+0.37%The inland waterway leg between the Corn Belt and the Gulf export elevators, which is the cheapest and the most weather-exposed of the three inland modes.index, 2017 = 100, published weekly, observation of 2026-10-07, measured against 2026-09-30. USDA Agricultural Marketing Service, Grain Transportation Report.
- US Gulf to Japan, grain vessel192.6-0.33%The seaborne leg of a Gulf export cargo. A grain rate on a grain route, and not a general dry bulk or container rate.index, 2017 = 100, published weekly, observation of 2026-10-07, measured against 2026-09-30. USDA Agricultural Marketing Service, Grain Transportation Report.
- Pacific Northwest to Japan, grain vessel175.770.00%The shorter export route, which is why its level sits well under the Gulf one and why the two parting company is a routing story rather than a freight one.index, 2017 = 100, published weekly, observation of 2026-10-07, measured against 2026-09-30. USDA Agricultural Marketing Service, Grain Transportation Report.
- Deep sea freight572.97-0.08%The only seaborne rate here that is not grain-specific. Monthly and indexed, so it carries the direction of ocean freight and never a quotable rate.index, published monthly, observation of 2026-10-01, measured against 2026-09-01. US Bureau of Labor Statistics producer price indexes, retrieved from FRED.
USDA's rates cover grain and refrigerated produce, which makes them a directional read on US inland bulk freight rather than a rate for metals, energy or containers. The BLS indexes are national and monthly, so they carry direction and not a quotable price.
No free public container spot index, dry bulk index or tanker rate is published, so a containerised leg and a seaborne bulk leg outside grain carry the diesel price as the cost of the fuel and never as a rate.
Freight rates for grain are published by the USDA Agricultural Marketing Service in its weekly Grain Transportation Report. This product uses the FRED® API but is not endorsed or certified by the Federal Reserve Bank of St. Louis.
Across the complexes, macro context and what was refused
- Inflation pressure8 of the 10 names moving in this theme fell today, the largest being Coffee at -3.86%. That is consistent with easing input-cost pressure across energy, grains and softs together.from Brent, WTI, Gasoline, Corn, Wheat, Soybeans, Coffee, Cocoa
- Industrial demand3 of the 3 names moving in this theme fell today, the largest being Palladium at -4.47%. That is consistent with softer industrial and manufacturing demand, though copper on its own is not a growth indicator.from Platinum, Palladium, WTI
- Food pressure7 of the 7 names moving in this theme fell today, the largest being Coffee at -3.86%. That is consistent with easing pressure on food costs from the field and the feedlot.from Corn, Wheat, Soybeans, Soy oil, Hogs, Coffee, Cocoa
- Haven demand2 of the 2 names moving in this theme fell today, the largest being Silver at -2.07%. That is consistent with softer haven and monetary demand, which gold alone does not establish.from Gold, Silver
- Transportation fuel cost2 of the 3 names moving in this theme fell today, the largest being WTI at -1.30%. That is consistent with falling transport FUEL costs, which is a different number from a billed freight rate and is measured here from fuel prices alone.from WTI, Gasoline
- US Dollar Index102.29+0.44%
- 10Y Treasury5.28%+0.15%
- Sentiment composite54-5.06%
Secondary on purpose. These interpret the commodities above; they do not lead them.
Reading the diagrams
- Physical flowOne is physically transformed into, or directly contributes to, the other.
- DivergenceRelated markets behaving differently by more than their own recent history accounts for.
- ConvergenceA difference that had opened between two related markets is closing again.
- ConfirmationRelated markets moving in broadly the same direction.
- SubstitutionThe two can stand in for one another in some physical or economic use.
- Common driverBoth are being read against the same stored upstream measurement.